ESG
original term: environmental, social and governance (ESG) (Eng.) · czynniki ESG, ryzyka ESG, inwestowanie odpowiedzialne
Global-circulation concept — no documented lineage in Central Europe. jump to documentation ↓
Working Definition
ESG (environmental, social, and governance) is a set of environmental, social, and corporate governance criteria that an investor or lender incorporates into the analysis of a company alongside traditional financial data. In its technical sense, rooted in capital markets, ESG is a risk category: it asks how climate change, labor law, supply-chain vulnerabilities, or board quality might hit a company's future cash flows. In everyday usage, by contrast, ESG is often taken to mean “good corporate behavior” or a firm's positive impact on the world. Most controversies surrounding the term stem from failing to distinguish these two directions: the world's risk to the company (financial materiality) and the company's risk to the world (impact materiality) are fundamentally different questions, even when answered under the same three-letter acronym.
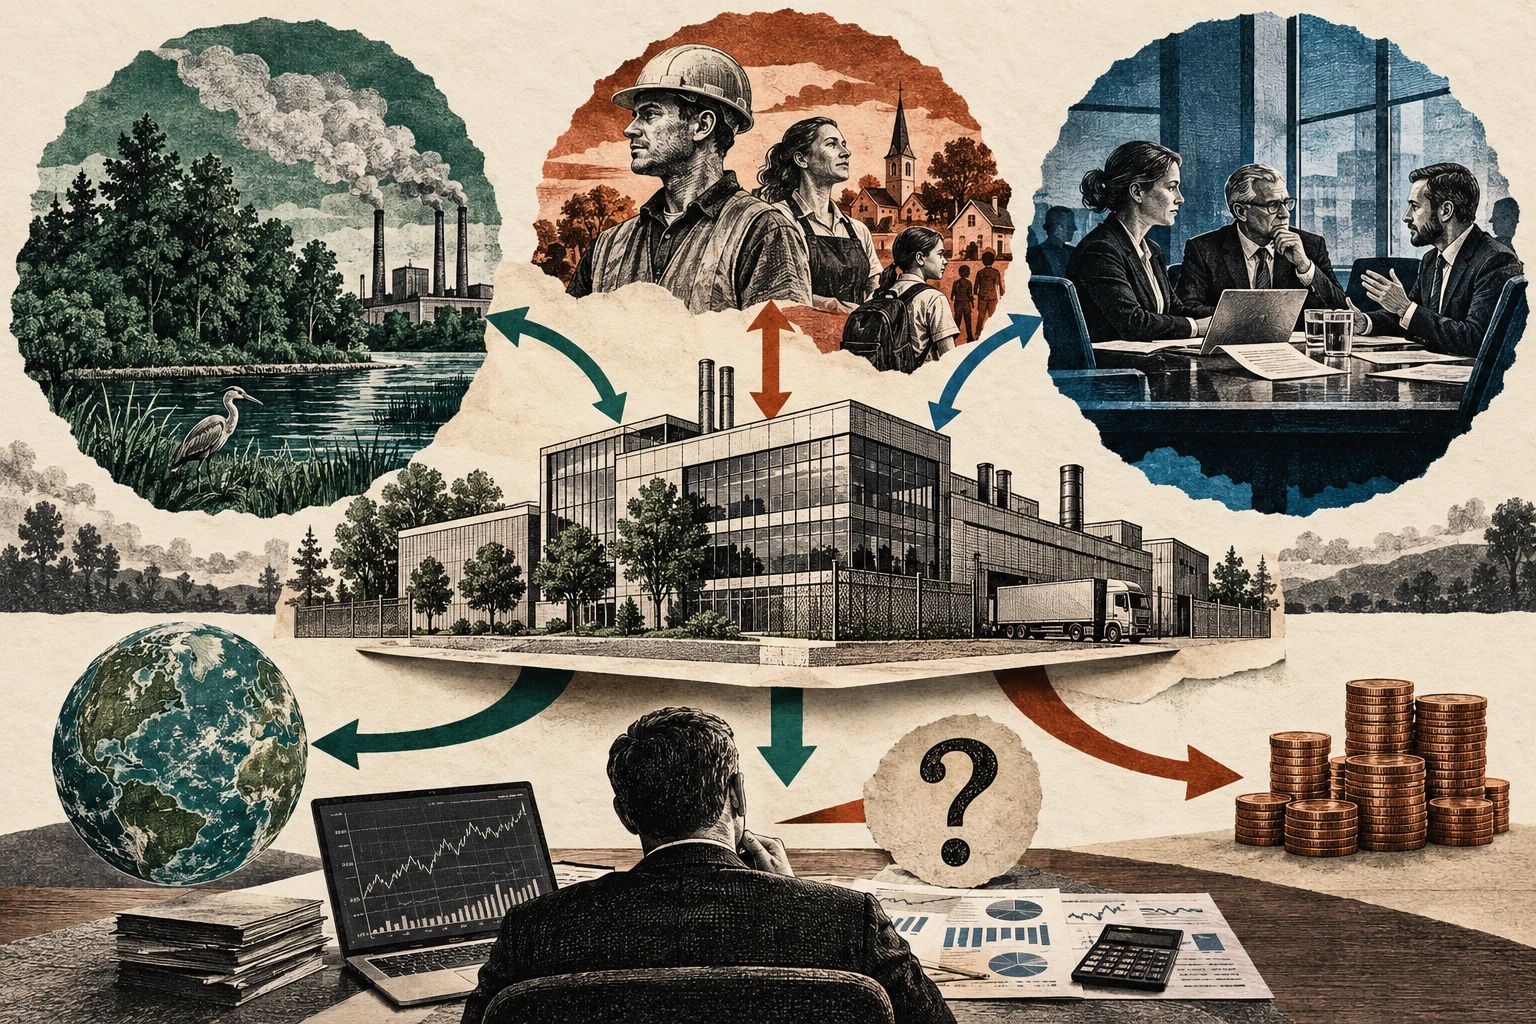
Evaluating an organization spans its environmental impact, treatment of people, and governance, though the mere presence of a report or score does not prove good outcomes.
AI-assisted illustration · conceptual metaphor View in visual quiz →Genesis and Global Lineage
The acronym entered circulation in 2004 with the report Who Cares Wins, prepared by a group of financial institutions at the invitation of the UN Secretary-General under the Global Compact. One year later, a landmark legal opinion by the law firm Freshfields Bruckhaus Deringer for the UNEP Finance Initiative concluded that integrating ESG factors into investment analysis is consistent with the fiduciary duty of asset managers handling other people's money—and in some cases is required by it. In 2006, the UN-backed Principles for Responsible Investment (PRI) were launched. Conceptually, ESG inherits from two older lineages: ethical screening and divestment campaigns (such as the anti-apartheid movement and the 1977 Sullivan Principles) and 1990s corporate management language, above all John Elkington's “triple bottom line” (people, planet, profit). What made ESG novel was its deliberate shift from ethics to risk: the core argument was no longer “this is the right thing to do,” but “this pays off or protects portfolios against loss.” From around 2015 onward, the concept was institutionalized by rating providers (MSCI, Sustainalytics) and the Financial Stability Board's Task Force on Climate-related Financial Disclosures (TCFD), before being partly captured by financial product marketing, where the “ESG” label often served sales rather than rigorous analysis.
Central European Lineage
We found no documented link between this concept and the intellectual history or historical experience of Central Europe.
We found no documented link between this concept and the intellectual history or historical experience of Central Europe (by our methodology, this means “none found,” not “none exists”; as of October 2026).
Why Now
The years 2018–2026 mark both the peak and the fracturing of ESG. Capital inflows into ESG-labeled funds surged until 2021, accompanied by mounting accusations of greenwashing: in 2021, Tariq Fancy, BlackRock's former chief investment officer for sustainable investing, called ESG a dangerous placebo that lulls regulators into inaction, and in 2022 Florian Berg, Julian Kölbel, and Roberto Rigobon demonstrated empirically that ESG ratings from different agencies diverge sharply. Starting in 2022, a coordinated anti-ESG campaign in the United States—featuring state laws barring asset managers deemed to “boycott” fossil fuels and the withdrawal of major asset managers from climate coalitions—turned the acronym into a partisan political marker, to the point that large funds stopped using the term altogether. In parallel, the European Union moved toward hard regulation: the Corporate Sustainability Reporting Directive (CSRD, 2022) expanded mandatory sustainability reporting to thousands of companies across Europe, only for the European Commission's 2025 Omnibus package to narrow that scope amid competitiveness concerns. Meanwhile, the US Securities and Exchange Commission adopted climate risk disclosure rules in March 2024 and subsequently ceased defending them in court, while the International Sustainability Standards Board (ISSB), established at COP26 in 2021, issued its IFRS S1 and S2 standards in 2023, absorbing the TCFD framework. Today the concept is indispensable not as a slogan, but as an analytical knife to separate what in ESG is genuine risk measurement, what is public policy by proxy, and what is mere marketing.
Explanatory Power
The ESG framework makes visible how costs that for decades remained external to a company's financial statements return through other doors: insurance premiums, cost of capital, litigation exposure, and access to supply-chain contracts. Three concrete examples illustrate its reach. First, consider an energy utility holding coal-fired assets: an “E” analysis highlights the risk of “stranded assets” whose book value will not survive climate policy, long before a loss registers on the current income statement. Second, take a gig-economy platform: the “S” pillar reveals that the entire business model hinges on worker classification, and thus on a single court ruling or legislative change. Third, look at a listed company controlled by the state treasury or a founder's family: the “G” pillar warns that a minority shareholder is buying not just a claim on earnings, but also the risk of strategic decisions made outside the boardroom to serve political or private goals. Across all three cases, ESG introduces not a new morality, but a longer time horizon for valuation.
Axes of Debate
Risk to the company versus the company's impact on the world
Asset managers and the ISSB standards defend the narrow version: ESG is about financial materiality for the investor, and a portfolio manager is not an arm of public policy. European Union regulators, civil society organizations, and proponents of “double materiality” reply that risk to the company's balance sheet is secondary to the real-world harm the company inflicts on ecosystems and communities. Strongest counterargument: The narrow financial-materiality version is internally coherent, but empty on the very issue that motivated the movement: a company can earn a stellar ESG rating because climate change does not threaten its quarterly earnings, even as its operations actively worsen the climate crisis. Nature of the dispute: substantive — it concerns whom the measurement is meant to serve, and neither camp can settle that conflict by definitional fiat.
Does ESG deliver superior financial returns?
Proponents, such as Alex Edmans, cite empirical studies showing superior long-term performance among firms that invest in employee well-being and governance; skeptics (including Aswath Damodaran and financial economists) point out that the evidence is noisy, period-dependent, and skewed by sector tilts (such as overweighting technology), arguing that profitability cannot simultaneously be an empirical hypothesis and an article of faith. Strongest counterargument: If high ESG scores reliably delivered excess returns, financial markets would price that advantage in and the alpha would disappear; a permanent return premium would require permanent market mispricing, which sits uneasily with the claim that ESG investors are better informed. Nature of the dispute: mixed — empirically testable in principle, but deployed by both sides as ammunition in a deeper normative dispute over the mandate of asset managers.
Private market solution versus substitute for public regulation
Milton Friedman in 1970 and his contemporary heirs argue that a corporate manager spending shareholders' money on social goals usurps the role of an elected parliament; from the opposite flank, critics like Tariq Fancy argue that ESG is harmful precisely because it mimics a solution and delays binding measures like a carbon tax. Strongest counterargument: Both critiques, though launched from opposite political flanks, assume the existence of a capable, uncaptured regulator; in jurisdictions where state capacity is weak or regulatory capture is entrenched, pressure from institutional lenders and investors is often the only functioning channel of corporate discipline. Nature of the dispute: substantive — a fundamental disagreement over the division of labor between capital markets and the democratic state, rather than a dispute over empirical facts.
Underappreciated Angle
The least examined link in the ESG chain is the letter “G,” even though governance determines whether the rest means anything at all. An environmental or social score is only as credible as the internal accountability for the underlying data and the consequences for falsifying it; where a supervisory board is a mere facade and a dominant shareholder—whether the state treasury, a founder, or a holding group—makes the real decisions offstage, “E” and “S” pledges become declarations without an addressee. For Central and Eastern Europe, this insight carries acute practical weight: because a large share of companies listed on regional exchanges (such as the Warsaw Stock Exchange) have a controlling state or private shareholder, the most consequential part of any ESG analysis concerns not emissions disclosures, but who actually governs the firm and how minority investors are protected. Seen in this light, the rating divergence documented by Berg, Kölbel, and Rigobon is not just a methodological flaw in weighting metrics, but a symptom of rating agencies' inability to measure corporate power.
One-Sentence Takeaway
ESG is not the conscience of capital, but an attempt to write into its balance sheet costs previously borne by others—and the fight over it is ultimately a fight over whether that ledger can be kept by the market or must be enforced by the state.
Related Concepts Network
How this concept reinforces, constrains, or complements other analytical frameworks in the corpus. View on graph →
-
Goodhart’s law reinforces
When an ESG rating becomes a target, firms optimize the metric rather than what it was meant to measure, and score divergence across rating agencies makes it easy to cherry-pick a favorable indicator.
-
Externalities complements
In its “risk to the firm” version, ESG measures how external costs return to the balance sheet; in its “impact” version, it asks who bears those costs—and the two questions are routinely conflated.
-
Net zero complements
Net-zero pledges are the most common content of the “E” pillar, and their credibility suffers from the same underlying problems with Scope 3 emissions data.
-
Tragedy of the commons complements
ESG is an attempt to get private capital to curb its own exploitation of the commons; critics point out that without binding regulation, such a mechanism lacks teeth.
-
Geoeconomic fragmentation in tension
The divergence of reporting regimes (the EU's CSRD, the anti-ESG backlash in US states, ISSB standards) is a textbook case of rules fragmenting along political lines.
-
Climate tipping points reinforces
Nonlinear climate risk is a strong argument that “E” risk cannot be priced from the historical data on which most ESG models rely.
-
Precautionary principle in tension
ESG promises to manage uncertainty through measurement and pricing; the precautionary principle holds that where harms are irreversible, measurement cannot replace a decision to refrain.
Reading Canon & Translation Bridge
Foundational texts, introductions, and critical perspectives—with availability of English and Polish editions.
-
foundational text 2004 · English
UN Global Compact (z udziałem grupy instytucji finansowych), Who Cares Wins: Connecting Financial Markets to a Changing World
The report that coined the acronym ESG: financial institutions convened by the UN argue that environmental, social, and corporate governance factors matter for valuation and risk management.
In English: original text written in English
In Polish: no Polish edition
-
foundational text 2005 · English
Freshfields Bruckhaus Deringer (dla UNEP Finance Initiative), A Legal Framework for the Integration of Environmental, Social and Governance Issues into Institutional Investment
The legal opinion that opened the door for pension funds: integrating ESG factors was deemed consistent with fiduciary duty and, under certain conditions, required by it.
In English: original text written in English
In Polish: no Polish edition
-
critical perspective 2022 · English
Florian Berg, Julian F. Kölbel, Roberto Rigobon, Aggregate Confusion: The Divergence of ESG Ratings
A paper in Review of Finance (vol. 26, no. 6, pp. 1315–1344) showing that ESG ratings across six major providers correlate at only 0.38–0.71, decomposing this divergence into differences in scope, measurement, and weight.
In English: original text written in English
In Polish: no Polish edition
-
critical perspective 1970 · English
Milton Friedman, A Friedman Doctrine: The Social Responsibility of Business Is to Increase Its Profits
The classic essay in The New York Times Magazine (September 13, 1970) from which every fundamental critique of ESG begins: a corporate executive spending other people's money on social goals acts outside the owners' mandate.
In English: original text written in English
In Polish: Polish edition not verified
-
critical perspective 2021 · English
Tariq Fancy, The Secret Diary of a Sustainable Investor
A three-part essay by BlackRock's former chief investment officer for sustainable investing, who calls ESG a dangerous “placebo” that distracts from government regulation—the most prominent insider critique.
In English: original text written in English
In Polish: no Polish edition
-
introduction & synthesis 2020 · English
Alex Edmans, Grow the Pie: How Great Companies Deliver Both Purpose and Profit
The best academic introduction to the thesis that stakeholder value and shareholder value need not be a zero-sum game; the author also shows where the empirical evidence remains weak.
In English: original text written in English
In Polish: Polish edition not verified
-
cross-disciplinary 1997 · English
John Elkington, Cannibals with Forks: The Triple Bottom Line of 21st Century Business
The source of the “triple bottom line” (people, planet, profit)—the management vocabulary from which ESG inherited its triad of categories before grafting onto it the logic of investment risk.
In English: original text written in English
In Polish: Polish edition not verified
Primary-Source Quotes
The results call for greater attention to how the data underlying ESG ratings are generated.