Network effects
original term: network effects (Eng.) · efekty sieci, network externalities, zewnętrzne efekty sieciowe
Central European lineage: 1 thread (anticipation) · 1892–1974 · jump to documentation ↓
Working Definition
A network effect occurs when the value of a good or service to an individual user increases with the number of other users of the same good or of compatible complementary goods. Economists distinguish direct network effects (a telephone or messaging app grows more valuable as more people can be reached on it) from indirect network effects (an operating system grows more valuable as more developers write software for its user base) and two-sided network effects (buyers attract sellers and sellers attract buyers on a marketplace). In casual business talk, the phrase is loosely applied to any advantage of size; in strict economics, it refers specifically to demand-side interdependence—as opposed to supply-side economies of scale—generating multiple equilibria, a critical-mass threshold, and winner-take-most tipping.
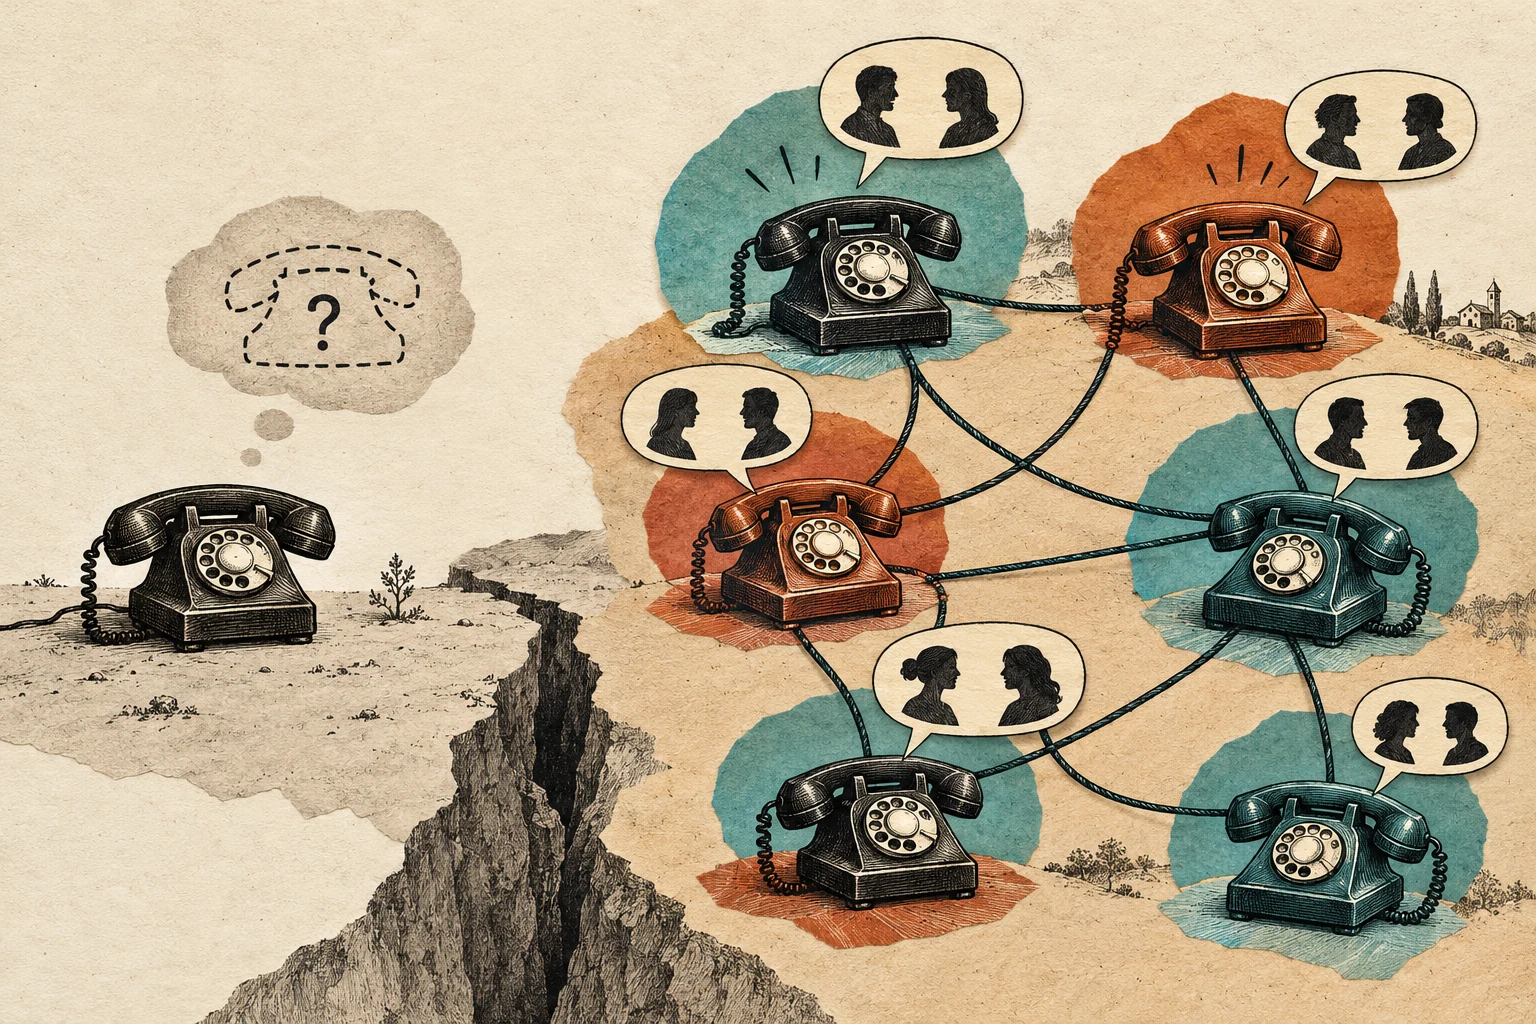
A telephone becomes more useful as more people can be reached through it; the value of participating depends on the presence of others.
AI-assisted illustration · conceptual metaphor View in visual quiz →Genesis and Global Lineage
The commercial intuition is older than the formal theory: in 1908 AT&T president Theodore Vail argued in Bell System annual reports that a telephone without connections has no value at all. The first mathematical model was published in 1974 by Jeffrey Rohlfs in the Bell Journal of Economics for communications demand: when each subscriber’s utility rises with other subscribers, a single price can support multiple equilibrium user sets (including zero), depending on initial conditions and expectations. The term network externalities was coined by Michael L. Katz and Carl Shapiro in a 1985 American Economic Review paper analyzing technical compatibility as a competitive weapon; with Joseph Farrell and Garth Saloner, they built the industrial-organization theory of standards wars (1985–1995), while W. Brian Arthur modeled increasing returns and lock-in at the Santa Fe Institute. In engineering and venture capital, the concept circulated via Metcalfe’s law—formulated by Ethernet co-inventor Robert Metcalfe around 1980 (network value grows as n2) and popularized by George Gilder in 1993—while Shapiro and Hal R. Varian’s Information Rules (1999) translated the economic models into internet strategy. Since then the concept has lived a double life: in antitrust economics as a rigorous structural condition requiring empirical proof, and in Silicon Valley pitch decks as a talisman attached to any growing user count.
Central European Lineage
A nineteenth-century anticipation of demand-side network effects comes from Carl Menger, founder of the Austrian School, whose career spanned Habsburg Central Europe: he studied law in Prague and Vienna, earned his doctorate at the Jagiellonian University in Kraków (1867), worked as an economic journalist in Lemberg (Lwów, now Lviv) and Vienna, and from 1873 held a chair at the University of Vienna. In his 1892 Economic Journal paper On the Origin of Money (translated from his German article Geld), Menger explained how money emerges spontaneously without state decree out of differences in the saleableness (Absatzfähigkeit, or liquidity) of commodities. Every trader gains by exchanging less saleable goods for more saleable ones even without consuming the latter; perceptive individuals do so first, others imitate their success, and the most saleable commodity comes to be accepted “not only by many, but finally by all.” Section VII opens with the observation that once a commodity becomes money, that very fact “has in the first place the effect of substantially increasing their originally high saleableness.” That is a positive demand-side feedback loop where the utility of adopting a medium of exchange rises with the number of other adopters—the exact mathematical structure Rohlfs, Katz, and Shapiro formalized eighty years later for telecommunications and standards, without citing Menger.
Documented regional lineage · Link: 1. Compiled: October 2026.
-
anticipation 82 years
Central European Source: Carl Menger, “On the Origin of Money (przekład Caroline A. Foley; pierwotnie „Geld”, 1892)”; Vienna, Austria-Hungary (now Austria), 1892
Global Circulation: network effects (network externalities) — Jeffrey Rohlfs; Michael L. Katz i Carl Shapiro, 1974
anticipation
82 yearsCarl Menger, “On the Origin of Money (przekład Caroline A. Foley; pierwotnie „Geld”, 1892)”
1892 · Vienna, Austria-Hungary (now Austria)
network effects (network externalities)
1974 · Jeffrey Rohlfs; Michael L. Katz i Carl Shapiro
- Claim & Connection
- In his 1892 “Economic Journal” article on the origin of money, Menger—who studied in Prague and Vienna, earned his doctorate in Kraków, worked as an economic journalist in Lemberg (Lwów) and Vienna, and held a chair at the University of Vienna—describes a self-reinforcing adoption mechanism: the most saleable commodity is accepted by a growing circle of market participants, and once it becomes money its saleableness increases further still, because every individual has an interest in accepting what others accept. This is an early formulation of a positive demand-side network effect; no evidence has been found that Rohlfs or Katz and Shapiro drew on Menger.
- Source Documentation
-
- primary source Carl Menger, „On the Origin of Money”, przeł. C.A. Foley, The Economic Journal, Vol. 2, No. 6, 1892, s. 239–255; reprint Ludwig von Mises Institute, Auburn 2009; end of Section VI: acceptance of the most saleable goods “not only by many, but finally by all”; Section VII, opening sentence: becoming money “has in the first place the effect of substantially increasing their originally high saleableness”. cdn.mises.org ↗
- biographical record Carl Menger, hasło w anglojęzycznej Wikipedii; biographical section: law studies in Prague and Vienna, doctorate at Jagiellonian University in Kraków, journalism at the “Lemberger Zeitung” and “Wiener Zeitung,” chair at the University of Vienna from 1873. en.wikipedia.org ↗
- reception / translation Jeffrey Rohlfs, „A Theory of Interdependent Demand for a Communications Service”, Bell Journal of Economics, Vol. 5, No. 1, 1974, s. 16–37; abstract: utility of a communications service increases with the number of subscribers; equilibrium user sets. ideas.repec.org ↗
- Historical Context
- Menger’s intellectual formation spanned Prague, Vienna, Kraków, and Lemberg across Habsburg Central Europe; Vienna is listed as the place where the 1892 work was produced. The German original “Geld” in the Handwörterbuch der Staatswissenschaften (1892) was not inspected directly; citations refer to the 1892 English version in The Economic Journal. The year on the global side marks Rohlfs (1974), while the term “network externalities” was coined by Katz and Shapiro (1985).
Why Now
Between 2018 and 2026 network effects moved from business-school courses into landmark antitrust trials and statutory regulation. The US House antitrust report on digital markets (2020) and federal suits by the DOJ and FTC against Google, Meta, Amazon, and Apple rest on the premise that direct and indirect network effects in search, social graphs, and app stores make dominant platforms self-entrenching. The European Union’s Digital Markets Act (DMA, 2022) codifies this logic: “gatekeepers” are designated because network effects and data loops create high entry barriers, and the DMA’s mandate requiring dominant messaging apps (such as WhatsApp) to open up to interoperability directly attempts to sever a network effect from single-firm ownership. Meanwhile, Elon Musk’s 2022 acquisition of Twitter and subsequent migrations toward Mastodon, Bluesky, and Threads served as a live experiment in critical mass: showing that an incumbent network can degrade yet retain users when the coordination cost of moving one’s social graph exceeds individual dissatisfaction. Finally, since 2023 debate has erupted over whether frontier AI chatbots enjoy true network effects at all: because one user’s prompt does not directly benefit from another user’s presence, the moat in foundation models may be supply-side compute rather than demand-side lock-in.
Explanatory Power
The concept separates an advantage rooted in a superior product from an advantage rooted in everyone else having already coordinated on a focal point. First, it explains why regional marketplace incumbents—such as Poland’s Allegro against eBay in the 2000s, or local classifieds across Asia and Europe—repeatedly defeated richer global giants: buyers went where local sellers were, and sellers stayed where buyers were, a two-sided loop no marketing budget could break without migrating both sides at once. Second, it shows why price competition alone cannot dislodge a networked monopoly: even a superior, zero-price rival fails if the value resides in the existing user graph rather than the software code. Third, it explains why subsidizing one side of a two-sided market (free consumer accounts, below-cost consoles, driver bonuses) is not classic predatory pricing, but an upfront investment to push adoption past the critical-mass threshold above which demand becomes self-sustaining.
Axes of Debate
Are network effects genuine market-failure “externalities”
Writing from the Chicago School tradition, Stan J. Liebowitz and Stephen E. Margolis (Journal of Economic Perspectives, 1994) argued that Katz and Shapiro’s term network externalities is tendentious because it implies an uncompensated market failure, whereas most network effects are internalized by the platform owner or solved through private pricing and standards bodies. Strongest counterargument: Internalization by a proprietary platform owner does not make the policy problem disappear—it transforms it into a distributional and antitrust problem: the platform owner captures monopoly rents on a collective asset (the network of interactions) that the users themselves jointly create. Nature of the dispute: substantive — it concerns who holds property rights over the surplus generated by user-to-user interdependence.
Do network effects lock markets into inferior standards
W. Brian Arthur and Paul David (in his famous 1985 study of the QWERTY keyboard) argue that under strong network effects, historical accidents and early adoption leads can lock an entire economy into an objectively inferior technical standard; Liebowitz and Margolis reply that the canonical historical cases (QWERTY versus Dvorak, VHS versus Betamax) collapse under archival scrutiny and that markets overcome lock-in whenever the efficiency gains of a new standard truly exceed switching costs. Strongest counterargument: Even if historical hardware examples like QWERTY are debated, digital platform markets exhibit documented collective switching traps where millions of users openly prefer an alternative protocol yet remain stuck until a coordinated shock or regulatory interoperability mandate lowers the transition barrier. Nature of the dispute: mixed — an empirical dispute over specific historical case studies is entangled with a broader ideological clash over the self-correcting capacity of markets.
Metcalfe’s n2 law versus diminishing marginal value of connections
Computer scientists and telecom economists Bob Briscoe, Andrew Odlyzko, and Benjamin Tilly (“Metcalfe’s Law is Wrong,” IEEE Spectrum, 2006) point out that Metcalfe’s n2 formula assumes every potential connection in a network is of equal value, which is false in every human and technical network (we communicate intensely with a few nodes and barely at all with the rest), proposing instead that network value grows only as n \log n. Strongest counterargument: Defenders of Metcalfe’s law point to empirical curve-fitting exercises on historical revenue and user data from Facebook and Tencent (2013–2015) that track an n2 trajectory more closely than n \log n—though critics reply that platform ad revenue measures monetization intensity rather than social utility. Nature of the dispute: substantive — it matters directly for valuing networked businesses and estimating when a growing network hits congestion, spam, and dilution costs (negative network effects).
Underappreciated Angle
Standard strategy guides treat network effects purely as an impenetrable moat protecting the winner. What is far less appreciated is that the exact same mathematical feedback loop operates in reverse once a network slips below a local density threshold. When a conventional manufacturer loses 15 percent of its customers, its product still works just as well for the remaining 85 percent; when a communications network or two-sided marketplace loses the most active 15 percent of its nodes, the service immediately becomes less valuable for everyone left behind, prompting the next cohort to leave and accelerating the unraveling. Networked systems therefore rarely decline gradually: they appear unassailable for years while dissatisfaction quietly accumulates, and then—once a focal event coordinates expectations around an exit—collapse with shocking speed (as seen in the rapid implosions of MySpace, Digg, or once-dominant local messaging apps). As Carl Menger already saw in 1892 for commodity money, a network good is held aloft not by physical hardware, but by a shared second-order belief about what everyone else will accept tomorrow—making networked dominance simultaneously more durable against incremental product competition and more brittle against a sudden shift in collective expectations.
One-Sentence Takeaway
A network effect resides not in the product itself, but in users’ expectations about where other users will be—which is why it can prop up an inferior platform for a decade and unravel it in a single season once those expectations tip.
Related Concepts Network
How this concept reinforces, constrains, or complements other analytical frameworks in the corpus. View on graph →
-
Platformization reinforces
Two-sided platforms are institutional machines built to capture indirect network effects between distinct user groups that could not cheaply coordinate without an intermediary.
-
Enshittification complements
Cory Doctorow describes what happens after network effects lock users in: once collective switching costs are high enough, a platform can degrade service quality and extract rents without losing critical mass.
-
Path dependence reinforces
Increasing returns to adoption mean that an early, sometimes accidental lead by one technical standard can become locked in even if a superior alternative later appears.
-
Adversarial interoperability constrains
Unilateral or mandated technical interoperability strips an incumbent platform of its exclusive grip on the network’s value by letting outsiders plug into its user base without permission.
-
Moloch and coordination failure complements
Staying on an inferior social platform simply because everyone else is still there is a classic coordination trap: everyone would prefer to move together, yet nobody wants to move alone.
-
Creative destruction in tension
Schumpeterian competition assumes that monopoly rents are transient, whereas strong network effects explain why digital monopolies prove far more durable than textbook creative destruction predicts.
Reading Canon & Translation Bridge
Foundational texts, introductions, and critical perspectives—with availability of English and Polish editions.
-
foundational text 1974 · English
Jeffrey Rohlfs, A Theory of Interdependent Demand for a Communications Service
The first formal mathematical model in the “Bell Journal of Economics” in which a subscriber’s utility depends on the number of other subscribers, generating multiple equilibria and a critical-mass threshold.
In English: original text written in English
In Polish: no Polish edition
-
foundational text 1985 · English
Michael L. Katz, Carl Shapiro, Network Externalities, Competition, and Compatibility
The landmark paper in the “American Economic Review” that coined the term “network externalities” and linked it to firms’ strategic choices over technical compatibility.
In English: original text written in English
In Polish: no Polish edition
-
introduction & synthesis 1999 · English
Carl Shapiro, Hal R. Varian, Information Rules: A Strategic Guide to the Network Economy
Translates formal industrial organization into business strategy: critical mass, switching costs, standards wars, and positive feedback, written on the eve of the first dot-com boom.
In English: original text written in English
In Polish: Polish edition not verified
-
critical perspective 1994 · English
S. J. Liebowitz, Stephen E. Margolis, Network Externality: An Uncommon Tragedy
Distinguishes ordinary network effects from true uninternalized market externalities and challenges the empirical claim that networked markets routinely lock in inferior technologies.
In English: original text written in English
In Polish: no Polish edition
-
cross-disciplinary 1994 · English
W. Brian Arthur, Increasing Returns and Path Dependence in the Economy
Collects Arthur’s foundational papers on increasing returns to adoption and market tipping toward early leaders, modeled with non-ergodic stochastic processes rather than unique neoclassical equilibria.
In English: original text written in English
In Polish: Polish edition not verified
-
cross-disciplinary 1892 · English
Carl Menger, On the Origin of Money
A nineteenth-century account of money as an institution emerging spontaneously from self-reinforcing acceptability—read today as the earliest clear analysis of a network good.
In English: original text written in English
In Polish: Polish edition not verified
Primary-Source Quotes
When the relatively most saleable commodities have become “money,” the great event has in the first place the effect of substantially increasing their originally high saleableness.