Systems & Complexity #054
Principal–agent problem
original term: principal–agent problem (Eng.) · problem agencji, problem pryncypała i agenta, koszty agencji
Global-circulation concept — no documented lineage in Central Europe. jump to documentation ↓
Working Definition
The principal–agent problem arises whenever one party (the principal) delegates action or decision-making authority to another (the agent) to act on the principal’s behalf, but cannot fully observe the agent’s effort or private information, while the two parties’ interests diverge. Goal divergence combined with information asymmetry gives the agent room to pursue self-interest at the principal’s expense; the costs the principal incurs to curb this divergence (monitoring, incentive alignment), the costs the agent incurs to signal trustworthiness (bonding), and the welfare loss that remains despite both efforts together constitute agency costs. In colloquial business talk, “agency problem” simply means that hired executives do not care for a company the way an owner does; in technical microeconomics, it is the formal design problem of crafting an incentive contract that maximizes the principal’s objective given that a rational, risk-averse agent will optimize against whatever rules are written.
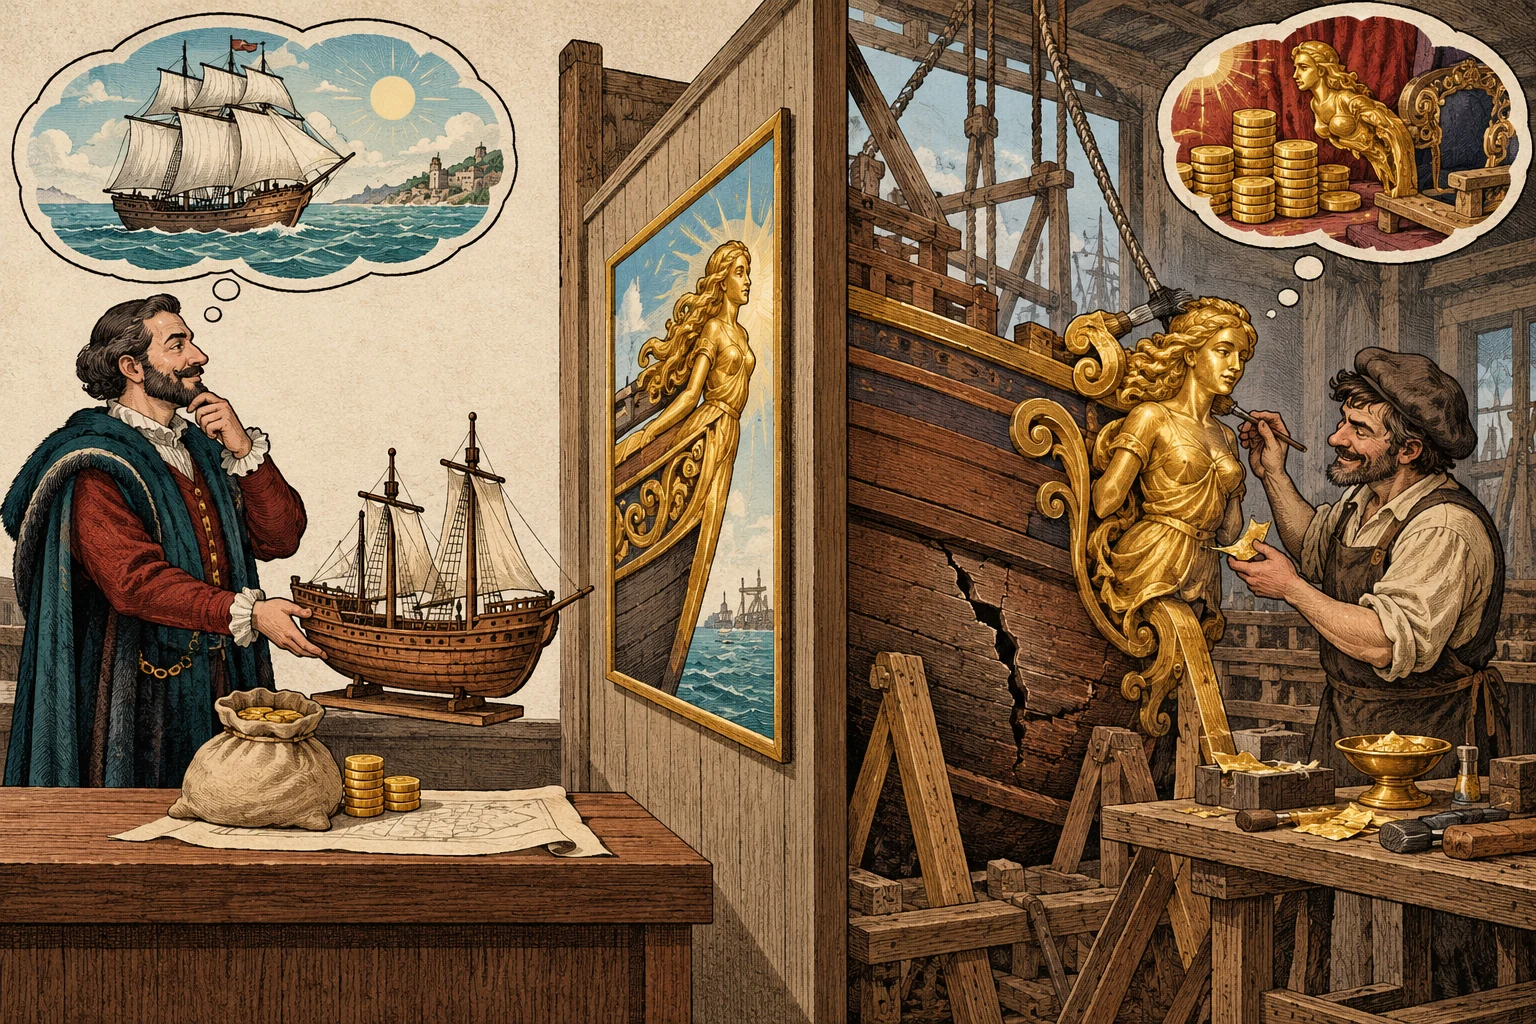
The owner wants a seaworthy ship while the contractor directs effort toward ornate trim tied to their own reward, and the partition shows limited visibility into actual work.
AI-assisted illustration · conceptual metaphor View in visual quiz →Genesis and Global Lineage
While Adam Smith already observed in The Wealth of Nations (1776) that the directors of joint-stock companies, managing “other people’s money,” cannot be expected to watch over it with the same anxious vigilance as partners in a private firm, and Adolf Berle and Gardiner Means documented the modern “separation of ownership and control” in 1932, the formal concept matured in American economics in the 1970s. Stephen Ross (1973) posed “the principal’s problem” as the mathematical selection of an optimal compensation rule under uncertainty, and Michael Jensen and William Meckling (1976) integrated it into corporate finance and property-rights theory—defining agency costs, modeling the firm as a nexus of contracts, and explaining how debt and equity structures balance competing agency conflicts. Bengt Holmström (1979) and James Mirrlees supplied the contract-theoretic machinery for moral hazard under unobservable effort, including the informativeness principle. In the 1980s and 1990s the framework expanded into political science (voters as principals, politicians and bureaucrats as agents) and corporate law. Along the way it was co-opted by Wall Street and executive-compensation consultants, who reduced a subtle theory of incomplete contracts to the slogan “pay for performance”—turning stock options from a cure for agency costs into a driver of short-term earnings manipulation.
Central European Lineage
We found no documented link between this concept and the intellectual history or historical experience of Central Europe.
We found no documented link between this concept and the intellectual history or historical experience of Central Europe (by our methodology, this means “none found,” not “none exists”; as of October 2026).
Why Now
Between 2018 and 2026, three developments gave the principal–agent framework fresh urgency. First, algorithmic management on digital labor platforms: a ride-hail driver, courier, or content creator acts as an agent monitored continuously by an algorithmic principal that controls dispatch, pricing, and ratings more tightly than any nineteenth-century factory foreman—making legal battles over platform workers’ status (such as the 2021 UK Supreme Court Uber ruling and the 2024 EU Platform Work Directive) disputes over whether algorithmic control creates an employment relationship. Second, artificial intelligence alignment: since 2022, researchers studying large language models and autonomous “AI agents” have framed reward hacking and specification gaming explicitly as principal–agent failures, where a model trained via reinforcement learning optimizes the literal proxy reward rather than the human principal’s intended goal. Third, post-pandemic corporate governance shocks—from the collapse of FTX in 2022 and the failure of Silicon Valley Bank in 2023 to recurring European debates over political patronage on the supervisory boards of state-owned enterprises (such as Poland’s spółki Skarbu Państwa)—have reignited scrutiny of who actually monitors the monitors.
Explanatory Power
The framework reveals that many apparent organizational “blunders” are in fact rational responses by agents to poorly structured incentives and observability gaps rather than incompetence or malice. Consider three illustrations. First, fee-for-service healthcare: a hospital or physician reimbursed per procedure performs more diagnostic tests and surgeries not out of greed, but because the payer (the insurer or national health fund) cannot directly observe clinical necessity and therefore pays for what it can count. Second, state-owned enterprises in parliamentary democracies: management faces two principals at once—dispersed citizen-taxpayers who want long-term enterprise value and the ruling coalition’s ministers who appoint the supervisory board and want short-term political patronage or cheap tariffs—and executives rationally serve the principal who holds the power to fire them. Third, active asset management: a mutual-fund manager compensated as a fixed percentage of assets under management maximizes asset gathering and hugs the benchmark index to avoid career-ending underperformance, rather than maximizing risk-adjusted net returns for savers. In all three cases, the concept redirects reform from preaching ethics to redesigning contracts and information flows.
Axes of Debate
Opportunistic contract design versus stewardship and intrinsic motivation
Management scholars (most famously Sumantra Ghoshal, 2005), organizational psychologists, and proponents of stewardship theory argue that agency theory’s baseline assumption of self-seeking opportunism becomes a self-fulfilling prophecy: subjecting professionals (doctors, teachers, executives) to intrusive monitoring and high-powered financial carrots crowds out intrinsic motivation, professional norms, and trust. Strongest counterargument: Contract economists reply that institutional design does not assume every agent is a knave, only that governance rules must remain robust when knaves appear—and that historical evidence for relying on unmonitored managerial stewardship in large corporations is sobering. Nature of the dispute: substantive — whether extrinsic financial incentives crowd out intrinsic motivation is an empirical question, and behavioral economics has shown that crowding-out is real in specific institutional settings.
Single-principal models versus multiple principals and multitasking
Political scientists and public-administration scholars point out that the textbook single-principal model misfires in public agencies, hospitals, and universities, where an agent answers simultaneously to parliament, ministries, courts, professional peers, and citizens, and where high-powered incentives attached to easily measured outputs starve unmeasured public missions (teaching quality, long-term resilience). Strongest counterargument: Bengt Holmström and Paul Milgrom’s multitasking model (1991) and Bernheim and Whinston’s common agency theory (1986) incorporate this critique directly into formal contract theory: when an agent performs multiple tasks of unequal measurability or serves competing principals, the mathematically optimal contract deliberately uses low-powered incentives (such as fixed civil-service salaries). Nature of the dispute: mixed — advanced contract theory fully accounts for the problem, yet real-world “New Public Management” reforms routinely applied the naive single-metric textbook version, making the practical critique valid.
Shareholder primacy versus stakeholder governance
Corporate legal scholars (such as Lynn Stout) and heterodox economists argue that Jensen and Meckling smuggled a normative ideology into a positive model: by casting shareholders as “the principals” and executives as “their agents,” they legitimized shareholder-value maximization, even though corporate law makes directors fiduciaries of the corporate entity itself rather than agents of stockholders. Strongest counterargument: Defenders of shareholder-focused accountability reply that an agent told to serve five competing stakeholder groups (shareholders, workers, suppliers, local communities, the climate) without a single objective tradeoff rule is accountable to none of them, turning “stakeholder capitalism” into a convenient shield for managerial self-dealing. Nature of the dispute: substantive — both sides agree on the mechanics of managerial discretion while clashing over legal doctrine and the empirical consequences of multi-objective mandates.
Underappreciated Angle
The principal–agent relationship is recursive, and its most revealing real-world form is a long chain in which every “principal” is simultaneously someone else’s agent. A corporate board of directors monitors the CEO, but the directors are agents of institutional shareholders; the pension fund or asset manager holding those shares is an agent of future retirees; the financial regulator overseeing the pension fund is an agent of a parliamentary committee, which is an agent of voters. Along such a delegation chain, agency costs do not merely add up—they compound, because each intermediary layer introduces its own career incentives, reporting horizons, and observability blind spots. At the very end of the chain stands not a vigilant owner, but millions of dispersed citizens or savers who face a classic collective-action problem and rationally do not read 300-page proxy statements. This explains why corporate governance rituals, compliance audits, and ESG ratings so often degenerate into costly theater: adding another layer of watchdogs creates another principal–agent problem. The decisive diagnostic question for any oversight architecture is not “who guards the agent?” but “how many links separate the decision-maker from the ultimate bearer of the residual risk?”
One-Sentence Takeaway
Before blaming an organization’s failure on incompetence or bad character, check whose interests the agent’s contract actually rewards and what their principal is capable of observing.
Related Concepts Network
How this concept reinforces, constrains, or complements other analytical frameworks in the corpus. View on graph →
-
Information asymmetry reinforces
The agency problem exists only because the principal observes less than the agent; without information asymmetry, a complete contract could simply stipulate the exact optimal action.
-
Goodhart’s law complements
Every proxy metric by which a principal attempts to discipline an agent becomes a target for strategic gaming and ceases to measure the underlying goal.
-
Skin in the game reinforces
Taleb’s maxim is the broader ethical counterpart of the alignment mechanism that Jensen and Meckling formalized as managerial equity ownership and downside exposure.
-
Rent-seeking complements
An agent who diverts organizational surplus into private perks or empire-building practices rent-seeking inside the firm rather than lobbying the state.
-
Moloch and coordination failure complements
A chain of agents, each rationally optimizing their own contractual KPI, regularly produces a macro-outcome that none of them—and no principal—actually wants.
-
AI alignment reinforces
Aligning advanced AI systems with human intentions is structurally a principal–agent problem with an agent whose internal objective function cannot be inspected directly.
Reading Canon & Translation Bridge
Foundational texts, introductions, and critical perspectives—with availability of English and Polish editions.
-
foundational text 1976 · English
Michael C. Jensen, William H. Meckling, Theory of the Firm: Managerial Behavior, Agency Costs and Ownership Structure
The landmark article in the “Journal of Financial Economics” (vol. 3, no. 4, pp. 305–360) that defined agency costs (monitoring, bonding, residual loss) and framed the corporation as a nexus of contracts.
In English: original text written in English
In Polish: Polish edition not verified
-
foundational text 1973 · English
Stephen A. Ross, The Economic Theory of Agency: The Principal's Problem
The concise paper in the “American Economic Review” (vol. 63, no. 2, pp. 134–139) that first posed the “principal–agent” relationship as a formal mathematical problem of optimal fee schedules under uncertainty.
In English: original text written in English
In Polish: Polish edition not verified
-
foundational text 1979 · English
Bengt Holmström, Moral Hazard and Observability
“Bell Journal of Economics” (vol. 10, no. 1, pp. 74–91): formalizes optimal contracting under unobservable effort and proves the informativeness principle governing which performance signals belong in a contract.
In English: original text written in English
In Polish: Polish edition not verified
-
introduction & synthesis 1980 · English
Eugene F. Fama, Agency Problems and the Theory of the Firm
“Journal of Political Economy” (vol. 88, no. 2, pp. 288–307): argues accessibly that managerial labor markets and outside reputation discipline executives even when dispersed shareholders cannot monitor them directly.
In English: original text written in English
In Polish: Polish edition not verified
-
critical perspective 2005 · English
Sumantra Ghoshal, Bad Management Theories Are Destroying Good Management Practices
The most influential critique from management studies: taught in business schools as a law of nature, agency theory becomes a self-fulfilling prophecy that crowds out intrinsic professionalism and breeds the very opportunism it assumes.
In English: original text written in English
In Polish: Polish edition not verified
-
introduction & synthesis 1985 · English
Oliver E. Williamson, The Economic Institutions of Capitalism
The neighboring tradition of transaction-cost economics: demonstrates how internal hierarchy and incomplete relational contracts govern opportunism when market incentive schemes fail.
In English: original text written in English
In Polish: Polish edition not verified
-
cross-disciplinary 1970 · English
Albert O. Hirschman, Exit, Voice, and Loyalty
The political-science complement: a principal who cannot write a complete incentive contract still holds two levers—exit (selling shares, switching providers) and voice (protest, voting)—modulated by loyalty.
In English: original text written in English
In Polish: Polish edition not verified