Decision reversibility
original term: decision reversibility (Eng.) · decyzje typu 1 i typu 2, drzwi jednokierunkowe i dwukierunkowe, one-way door / two-way door
Central European lineage: 1 thread (anticipation) · 1944–2015 · jump to documentation ↓
Working Definition
Decision reversibility is the property of a choice measured by how much it costs—in money, time, reputation, or foregone options—to return to the status quo ante if the choice turns out to be wrong. Decisions that are cheap to undo (“two-way doors,” or Type 2 decisions in Jeff Bezos’s terminology) should be made quickly, by individuals or small teams, on imperfect data, because the cost of error is capped while the cost of delay compounds. Decisions that are prohibitively expensive or impossible to undo (“one-way doors,” or Type 1) justify slow deliberation, broad consultation, and paying for additional information. In technical economics (irreversibility theory and real options), reversibility is not a binary toggle but a continuous quantity: the option value preserved by keeping the ability to change course after new information arrives.
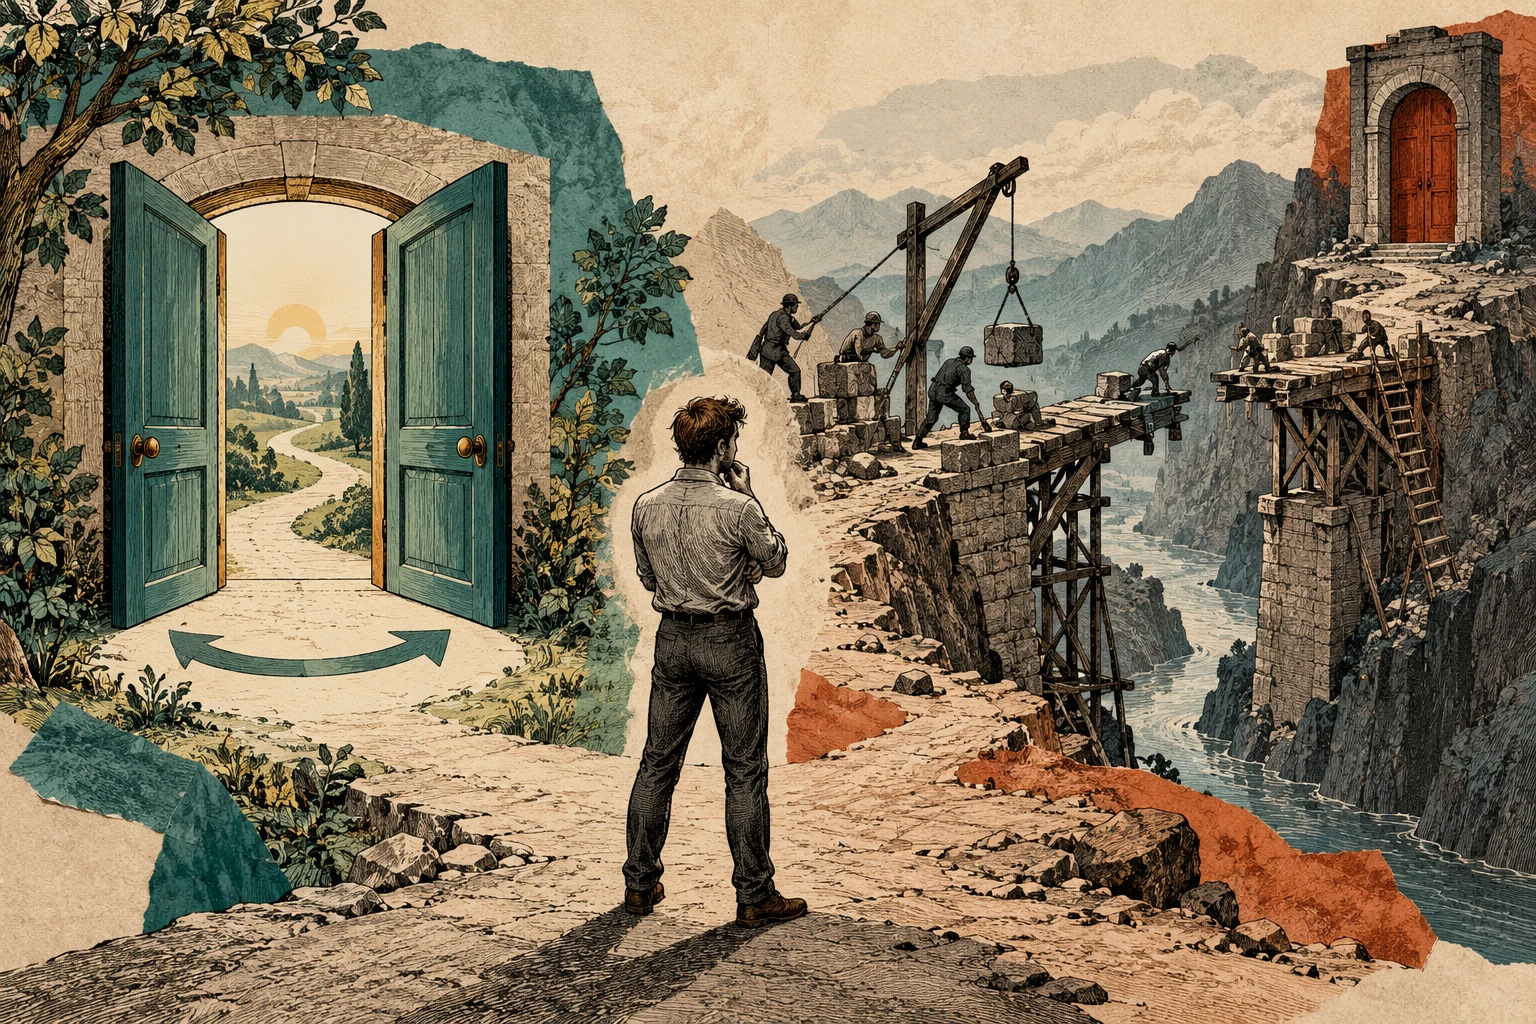
One doorway allows easy return while the other requires costly reconstruction; the degree of reversibility shapes how carefully a decision should be made.
AI-assisted illustration · conceptual metaphor View in visual quiz →Genesis and Global Lineage
The concept circulates in two largely independent traditions. The academic lineage began in 1974 with two simultaneous papers: Kenneth Arrow and Anthony Fisher in the Quarterly Journal of Economics demonstrated that when a policy choice involves an irreversible alteration of an environment (such as flooding a canyon for a dam), there exists a positive “quasi-option value”—a premium on delaying the irreversible commitment until scientific or economic uncertainty resolves; in the American Economic Review, Claude Henry independently proved the same result under the name irreversibility effect. Out of this foundation grew the theory of real options, synthesized in Avinash Dixit and Robert Pindyck’s Investment under Uncertainty (1994): irreversibility coupled with uncertainty gives waiting a quantifiable economic value, showing why naive net-present-value rules systematically overstate the case for investing immediately. The managerial lineage arose separately four decades later. In his 2015 Letter to Amazon Shareholders (published in April 2016), Jeff Bezos divided corporate choices into Type 1 (“one-way doors”) and Type 2 (“two-way doors”), warning that as organizations grow they reflexively apply heavyweight Type 1 approval processes to reversible Type 2 decisions, breeding institutional scar tissue and risk aversion. (Our source list dates Bezos’s formulation to 1997 because Amazon reprints its 1997 shareholder letter at the end of every annual report, though the Type 1 / Type 2 passage itself comes from the 2015 letter.) While Bezos’s binary rule simplifies continuous option pricing into a rough heuristic, that very simplicity carried it across product management, software engineering, and venture investing.
Central European Lineage
The closest intellectual ancestor to using reversibility as a meta-rule for institutional action comes not from neoclassical economics, but from the philosophy of science and politics of interwar Vienna. Karl Popper—educated at the University of Vienna from 1918, where he earned his doctorate in 1928 under the psychologist Karl Bühler before emigrating in 1937—contrasted “piecemeal social engineering” with “utopian” or holistic blueprint planning in The Poverty of Historicism (serialized in Economica in 1944–1945 and published as a book in 1957). Popper’s core argument for piecemeal reform is an argument from reversibility under uncertainty: small, targeted institutional adjustments allow us to observe unintended consequences early and walk back a mistake at tolerable social cost, whereas a comprehensive overhaul alters so many variables at once that errors cannot be isolated or undone without systemic coercion. Popper framed this as the political equivalent of falsifiable trial and error rather than as option pricing, and we found no evidence that Arrow, Fisher, Henry, or Bezos drew on his text. Yet the operational logic—match the scale and irreversibility of an intervention to the limits of your predictive knowledge—is an unmistakable anticipation of the modern framework.
Documented regional lineage · Link: 1. Compiled: October 2026.
-
anticipation 71 years
Central European Source: Karl Popper, “The Poverty of Historicism (trzy części w „Economica” 1944–1945; książka 1957)”; Vienna, Austria (formation); Christchurch, New Zealand (publication), 1944
Global Circulation: Type 1 and Type 2 decisions (one-way doors / two-way doors) — Jeff Bezos, 2015
anticipation
71 yearsKarl Popper, “The Poverty of Historicism (trzy części w „Economica” 1944–1945; książka 1957)”
1944 · Vienna, Austria (formation); Christchurch, New Zealand (publication)
Type 1 and Type 2 decisions (one-way doors / two-way doors)
2015 · Jeff Bezos
- Claim & Connection
- Educated at the University of Vienna (studying from 1918 and earning his PhD in 1928 under Karl Bühler), Popper argued in “The Poverty of Historicism” for the superiority of piecemeal social engineering over holistic utopian planning on the grounds that small, reversible steps make it possible to detect unintended consequences and correct errors before they become entrenched, whereas a sweeping blueprint precludes such mid-course reversal. This is an earlier deployment of corrigibility and reversibility as the primary criterion for choosing a mode of action; no evidence has been found that Bezos or the economic literature on irreversibility (Arrow and Fisher 1974, Henry 1974) drew on Popper.
- Source Documentation
-
- scholarly study Stephen Thornton, „Karl Popper”, The Stanford Encyclopedia of Philosophy; §1 (studies in Vienna from 1918, PhD 1928); §2 (publication dates of “The Poverty of Historicism”: Economica 1944–1945, book 1957); §8 and §10 (holistic blueprint planning vs. piecemeal engineering, detecting and correcting unintended consequences). plato.stanford.edu ↗
- reception / translation Jeff Bezos, „2015 Letter to Shareholders”, Amazon.com, Inc., kwiecień 2016 (SEC, Form 8-K, Exhibit 99.1); paragraphs on Type 1 and Type 2 decisions (one-way doors, two-way doors). sec.gov ↗
- Historical Context
- Popper’s primary text was not opened in this round; the summary of his argument relies on the secondary literature (SEP). Popper writes about the corrigibility of reforms rather than “decision reversibility” as a formal category; the parallel concerns the operational criterion rather than the terminology.
Why Now
Between 2018 and 2026 the distinction between one-way and two-way doors moved from Amazon’s executive memos into the everyday operating grammar of technology companies and policy debates. Product management playbooks, engineering Request for Comments (RFC) templates, and startup governance guides now routinely require teams to classify a proposed change by its reversal cost before deciding who needs to sign off on it. At the same time, the exact same criterion returned at macro scale in debates over frontier artificial intelligence: calls to pause or gate the deployment of open-weight foundation models—from the March 2023 Future of Life Institute open letter to international AI safety summits in 2023–2025—are structured explicitly as warnings that irreversible Type 1 decisions (releasing model weights that cannot be recalled from the internet) are being taken at the breakneck pace appropriate only to reversible Type 2 software patches. A third arena is climate and energy policy, where Earth-system tipping points and multi-decade infrastructure lock-in have made Arrow and Fisher’s quasi-option value a central argument against irreversible fossil-fuel capital commitments.
Explanatory Power
The concept reveals why most organizational arguments pitching “speed and boldness” against “prudence and process” are poorly framed: the right tempo is not a matter of leadership temperament, but a function of reversal cost. First, it explains the creeping paralysis of large institutions without blaming personal incompetence: it takes only a few high-profile blunders for compliance departments to impose a single heavyweight approval workflow on all decisions, silently taxing hundreds of reversible experiments with the process overhead designed for a one-way door. Second, it accounts for why corporate capital spending often lags behind textbook forecasts: when capital expenditure is irreversible and demand is volatile, waiting for clarity has high option value, so rational managers demand a hurdle rate well above the cost of capital. Third, it clarifies public policy design: a regulatory experiment equipped with a sunset clause or regional pilot is a two-way door that can be enacted on tentative evidence, whereas privatizing a natural monopoly, abolishing a constitutional court, or flooding a river valley is a one-way door demanding a much higher evidentiary bar. In every case, the question “are we sure we are right?” is preceded by “how much will it cost to walk back if we are wrong?”
Axes of Debate
Binary heuristic versus continuous real-options pricing
Real-options economists and quantitative decision analysts fault Bezos’s two-bucket typology for hiding what matters most: reversibility is a continuous spectrum that depends on switching costs, time horizons, and the rate at which new information arrives, and should therefore be priced rather than sorted into two boxes. Strongest counterargument: No operating organization can run a stochastic dynamic programming model for hundreds of daily product, pricing, and hiring choices; a crisp binary heuristic is cognitively cheap, shifts the burden of proof against bureaucratic defaults, and improves average decision velocity far more than an exact formula nobody uses. Nature of the dispute: substantive — both sides accept the same underlying economics of irreversibility, differing over the meta-cost of calculation in everyday organizational life.
Does irreversibility actually single out a distinct class of choices
Legal scholar Cass Sunstein and critics of the precautionary principle from cost-benefit analysis point out that because time flows in one direction, every choice is strictly irreversible (money spent and hours lived never return), so invoking “irreversibility” is vacuous unless one specifies the exact cost of restoration and the magnitude of the loss. Strongest counterargument: Defenders of the concept reply that Arrow and Fisher’s quasi-option value does precisely that: it measures the economic difference between trivial everyday irreversibility and commitments that foreclose the ability to act on forthcoming information. Nature of the dispute: mixed — the analytical demand to quantify switching costs is substantive, but the critique is also deployed rhetorically to disarm precautionary environmental regulation.
Reversible for whom
Sociologists of technology, labor economists, and platform critics observe that a decision that is a frictionless “two-way door” for an executive team is often a brutal one-way door for users, workers, or third-party developers: a company can roll back a product feature or shut down a division in an afternoon, but laid-off employees, bankrupted ecosystem partners, and leaked personal data cannot be rolled back. Strongest counterargument: From an analytical standpoint, the heuristic does not deny externalized costs; rather, it exposes them—once we ask “whose reversal cost is being counted?”, governance rules can explicitly reclassify decisions that impose irreversible external harm as Type 1 choices requiring external oversight. Nature of the dispute: substantive — it concerns the boundary of the accounting unit (firm versus society) and explains why internal corporate agility and public regulatory precaution regularly collide.
Underappreciated Angle
Reversibility is rarely a fixed fact of nature; most of the time, it is an engineered artifact. The very same decision can be a terrifying one-way door or a routine two-way door depending on whether someone previously invested in rollback infrastructure: feature flags and canary deployments in software, sunset clauses and pilot cohorts in legislation, breakup fee caps in contracts, or modular standards in industrial procurement. The highest leverage of the concept therefore lies not in passively classifying the decision sitting on your desk today, but in asking an upstream design question: what would we have to build so that this one-way door becomes a two-way door, and does that engineering cost less than the delay of a Type 1 deliberation process? Organizations that systematically invest in the machinery of cheap reversal can afford to move fast without gambling their survival; those that neglect it are condemned to choose between bureaucratic paralysis and reckless bets. In that sense, the most consequential Type 1 decisions an institution ever makes are the architectural choices that determine how many of its future decisions will be Type 2.
One-Sentence Takeaway
Before asking whether a decision is right, ask how much it will cost to undo if it turns out to be wrong—and let that price tag, not institutional habit, dictate how long you deliberate.
Related Concepts Network
How this concept reinforces, constrains, or complements other analytical frameworks in the corpus. View on graph →
-
Optionality complements
Reversibility is the option value of preserving the ability to change course; the real-options literature prices this exact difference between a reversible and an irreversible commitment.
-
Precautionary principle reinforces
The precautionary principle is at bottom a decision rule for high-stakes irreversible choices; stripped of the concept of irreversibility, it loses its analytical footing.
-
Path dependence reinforces
A decision usually becomes irreversible not through physical law, but through sunk costs, network lock-in, and self-reinforcing expectations described by path dependence.
-
Chesterton’s fence in tension
Chesterton demands full understanding before removing a rule; two-way-door logic suggests trying the removal and walking back through the door if the cost of reversal is genuinely low.
-
Antifragility complements
Preferring reversible decisions is a practical recipe for payoff convexity under uncertainty: capped downside if wrong, open upside if right.
-
Probabilistic thinking complements
Reversibility determines how much epistemic certainty is worth buying before acting: for two-way doors a rough estimate suffices, whereas one-way doors justify paying heavily for information.
-
Second-order effects constrains
Many decisions look reversible only in the first order; reputational fallout, habit formation, and altered expectations often lock a door that was supposed to swing both ways.
Reading Canon & Translation Bridge
Foundational texts, introductions, and critical perspectives—with availability of English and Polish editions.
-
foundational text 2016 · English
Jeff Bezos, 2015 Letter to Shareholders (Amazon.com, Inc.)
The concise source text of the concept in managerial circulation: introduces Type 1 (one-way doors) and Type 2 (two-way doors) decisions and warns against applying heavyweight Type 1 governance processes to reversible Type 2 choices.
In English: original text written in English
In Polish: no Polish edition
-
foundational text 1974 · English
Kenneth J. Arrow, Anthony C. Fisher, Environmental Preservation, Uncertainty, and Irreversibility
A classic paper in the “Quarterly Journal of Economics” (vol. 88, no. 2, pp. 312–319) where irreversibility first receives a formal price as “quasi-option value”: delaying an irreversible Commitment carries positive value because it preserves the ability to act on future information.
In English: original text written in English
In Polish: no Polish edition
-
foundational text 1974 · English
Claude Henry, Investment Decisions Under Uncertainty: The „Irreversibility Effect”
Published alongside Arrow and Fisher in the “American Economic Review” (vol. 64, no. 6, pp. 1006–1012), formulating the “irreversibility effect”: a decision-maker who anticipates learning new information should tilt toward the more flexible alternative.
In English: original text written in English
In Polish: no Polish edition
-
introduction & synthesis 1994 · English
Avinash K. Dixit, Robert S. Pindyck, Investment under Uncertainty
The definitive textbook synthesis of real-options theory (Princeton University Press), showing why irreversibility combined with uncertainty raises the value of waiting and explains the apparent “sluggishness” of capital investment.
In English: original text written in English
In Polish: Polish edition not verified
-
cross-disciplinary 1957 · English
Karl R. Popper, The Poverty of Historicism
A philosophical defense of steps that can be walked back: piecemeal social engineering as the political counterpart of falsifiable hypothesis testing (published in Polish underground in 1984 by Krąg and officially by PWN in 1999).
In English: original text written in English
In Polish: Polish edition not verified
-
critical perspective 2006 · English
Cass R. Sunstein, Irreversible and Catastrophic
A legal-economic critique in the “Cornell Law Review” (vol. 91, 2006): points out that since time moves forward, every decision is irreversible in some strict sense, so the concept is empty unless specified by restoration cost and magnitude of stakes.
In English: original text written in English
In Polish: no Polish edition
Primary-Source Quotes
Some decisions are consequential and irreversible or nearly irreversible – one-way doors – and these decisions must be made methodically, carefully, slowly, with great deliberation and consultation.